Buying real estate is an important event in the life of every person, every family. At the same time, it is also a responsible one, since it is associated with choice, money, and calculations. The question arises: how to buy an apartment profitably? Today, it is not necessary to collect the full amount and pay everything at once. There are additional financial instruments, you just need to understand all the intricacies.
Our experts have analyzed what available programs and other solutions are offered by the state, the bank in the real estate market. We will consider the pros and cons of all steps. We will also calculate how much it will cost two-room apartment in Kiev when buying, if you arrange a deferral from the developer, the e-Housing program, or a mortgage.
Ways to buy an apartment
There are four ways to pay for an apartment in Ukraine.
- Full payment. It is believed that this is the simplest and most hassle-free option among all. The buyer takes an apartment or a private house and makes a single payment. Additionally, here we can talk about the benefit due to the absence of any overpayments (except for notary services). If you buy housing in a new building, there is a very real chance of getting a good discount from the developer.
- Installment plan. Another acceptable solution. It involves paying the first installment, after which the amount is divided into payments (number of months).
- "eOselya". A state program that can be used by certain categories of citizens. The interest rate is quite low.
- Mortgage. The future borrower takes out a target loan for the purchase of real estate from a bank. In this case, the apartment serves as collateral.
As is clear, there are options for any occasion, even if the potential owner does not have enough funds to purchase housing.
Full payment
Full payment is a method of payment when the buyer comes with the full amount and immediately makes a deposit, after which he becomes the happy owner of the property without obligations to the developer or bank.
Of course, this option has its own advantages and disadvantages, and the key one is the provision of discounts. In addition, the cost of housing is fixed. There are no insurances and huge commissions, which is also great. Most importantly, housing is not a collateral instrument.
However, there are also disadvantages:
- lack of free money;
- risks, especially if the buyer invests in an apartment at the construction stage of the house;
- the likelihood of encountering scammers.
It is usually carried out according to the following scheme: first - deposit (reservation of the object), after which the ad is removed from all platforms. Next comes the signing of the contract - documents are collected, the buyer and seller meet at the notary or in the office. The deal is certified. Then - deposit of funds. The money is transferred to the seller, everyone is happy and satisfied.
Delay from the developer
Installment from the developer is an option when the buyer makes a partial payment over a specific period. He enters into an agreement with the company, while the apartment itself is not pledged.
What are the advantages of renting an apartment in installments:
- ease and simplicity – you don’t have to spend time confirming income, there is no need to mortgage property, or look for guarantors for approval;
- financial benefit – interest-free (or minimal) registration is offered; as a rule, no insurance is required, that is, there are no unnecessary costs;
- the possibility of choice - the future owner decides for himself during what period he will pay for the purchase, what the amount of payments will be.
There are, of course, disadvantages, and these include currency risks, since the cost often depends on the dollar exchange rate. In addition, we must not forget about the significant financial burden. Also, the conditions can sometimes change.
As for the time frame for arranging installment payments, it is usually possible to do this at any stage of building a house – with only a foundation pit, during the construction of walls and finishing works. The range of payment terms varies within different limits – from 1-3 years (standard) to 5-7 years.
The amount of the first payment depends on many circumstances. The minimum threshold is usually 10-30%, there are minor risks. The most optimal is considered to be the payment of half the amount (50%): so, the value of the property is fixed, and the interest rate is reduced, which is good in any case. There is also an option when the balance is paid in one payment immediately before the completion of construction.
How to arrange an installment payment for an apartment
Payment in installments is made according to the following algorithm:
- collection of documents (passport, code);
- choice of apartment;
- discussing details – about the down payment, monthly payment, schedules, whether the price will be fixed;
- accommodation booking;
- checking the transparency of the future deal.
Everything ends with the signing of documents and the first payment, and then - according to the terms of the concluded contract.
Payment under the eOselya program
"eOselya" – a program designed to support Ukrainian citizens in purchasing real estate. The main advantage is fairly low interest rates. Part of the funds are compensated by the state.
The program is available to the following categories of the population (preferential):
- military personnel, security forces;
- medical workers;
- teachers, lecturers;
- scientists;
- prosecutor:
Also participating can be:
- veterans, combatants, and their family members;
- IDPs;
- other citizens of Ukraine who do not have their own real estate, or the number of square meters does not meet the norm.
The lending conditions are quite simple. The first payment for an apartment is 20% of the cost of the housing. The maximum term for which the program is valid is 20 years (240 months). The interest rate changes after ten years.
Conditions areOselya
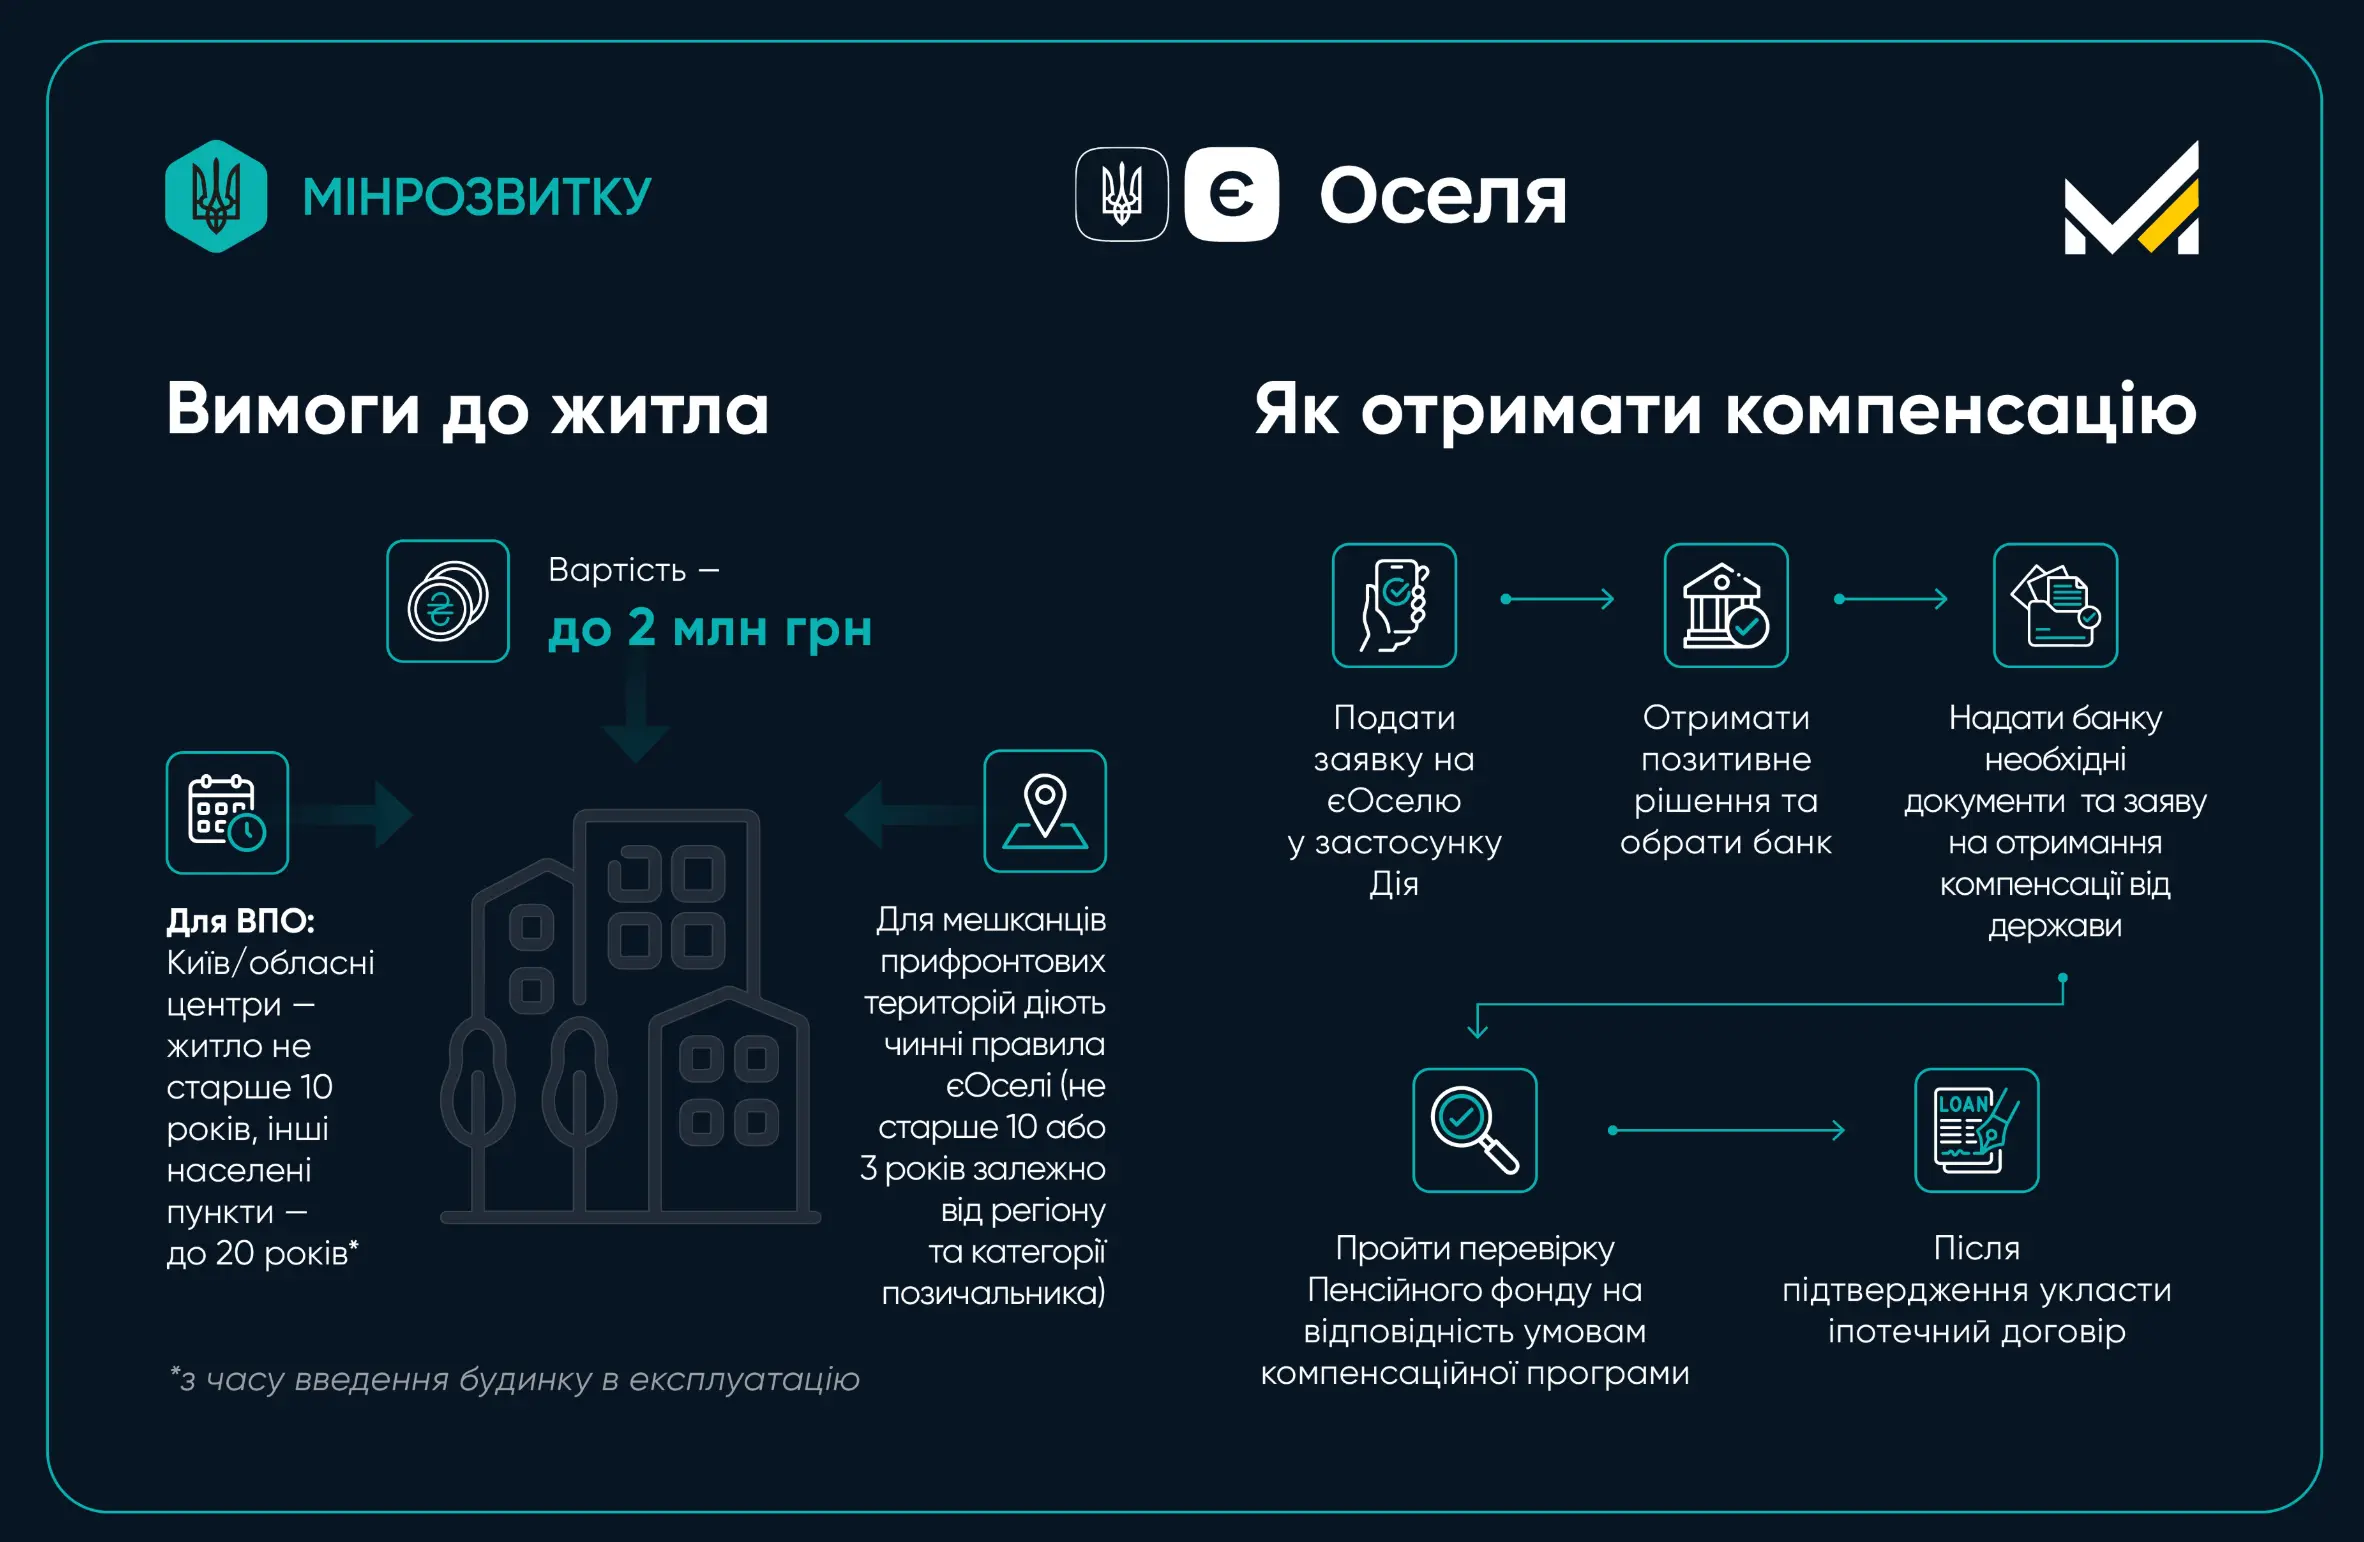
The interest rates are really convenient and profitable – 3% and 7%. Payment is made only in the national currency – hryvnia, which eliminates exchange rate fluctuations that affect the cost and amount of payments.
"eOselya" is considered a very strict program. There are certain requirements for everyone - both the borrower and the property. Let's start with the home buyer:
- credit history – participation in the program is complicated by late payments, outstanding loans or bankruptcy;
- age limit – from 18 years old, at the time of repayment the owner must be 70 years old;
- solvency – the presence of a stable income;
- property restrictions - the owner does not own an apartment with an area of more than 52,5 square meters (plus: 21 square meters for each family member);
- absence of sanctions.
You can buy an apartment, however, there are certain restrictions. The new building should not be older than 3-10 years, have accreditation from banks from the list. The area of the property is 52,5 square meters + 21 square meters for each family member.
Advantages and disadvantages of e-Oselya
The program has its pros and cons. Let's start with the pros:
- low interest rate compared to banks and financial companies;
- independence from the dollar;
- convenience and speed of registration – the application can be submitted through “Diya”;
- safety – a thorough inspection of the facility is carried out.
Among the disadvantages are the strict requirements, considerable costs for insurance and notary services, and dependence on the place of work and position.
Mortgage lending
A mortgage loan is a traditional, well-known financial instrument, when a contract and agreement are concluded with a bank. Both parties have their obligations here; the bank is protected from risks thanks to the collateral (apartment). Any citizen of Ukraine can apply for a mortgage.
A mortgage for a home is issued for a period of 20 years. With great financial capabilities, it is realistic to repay everything ahead of schedule. The annual interest rate ranges from 15-19%.
What are the requirements for a real estate buyer:
- clean credit history, without late payments and outstanding loans;
- providing a full package of documents;
- official employment for at least six months;
The housing must be legally clean, without illegal redevelopment. At the same time, if the future owner is looking for an apartment in a new building, the developer company must be accredited.
Conditions for obtaining a mortgage
Any citizen of Ukraine over the age of 21 can get a mortgage (provided that he or she is already 65 years old at the time of repayment). To get started, you need to make a down payment of 20-40% of the cost of the home (the more, the better).
Advantages and disadvantages
Advantages of taking out a mortgage:
- absolute freedom of action;
- access to credit for all;
- thorough inspection at all stages.
Among the disadvantages, it is worth noting significant overpayments, using the apartment as collateral, property, health, and life insurance.
Example of calculating the purchase of a home
It is important for the future owner to understand the benefits of each of the options considered, to calculate the amount in advance. To do this, you need to decide specifically on the type of property - what it is, how many rooms, where it will be located. As an example, it is worth considering two-room apartment in the Podilskyi district of Kyiv. This quiet and wonderful place, with convenient transport connections, is just a dream for couples. Housing can cost about 3.000.000 UAH (or 75.000 dollars).
Rescheduling
If we are considering purchasing a “two-story house” in installments, for example, at the construction stage, then approximately 50% of the amount is required for the first installment. Usually, a term of one and a half years (18 months) is given. Then the monthly payment is 83.333 UAH.
If the house is already put into operation, the payment is less, and the initial payment is 40% of the price. The interest rate is kept at 10%. The monthly payment is 38.500 UAH.
It should be noted that the amount is approximate, all information should be clarified with the developer.
"eOselya"
The interest rate plays a key role. If the buyer can get a mortgage at 3%, he pays 20% of the amount; this is approximately 600.000 UAH. Let's say it is taken for 20 years. Then the monthly payment will be 13.310 UAH. The overpayment is 194.000 UAH.
How are things going with 7%? The conditions are similar: the down payment is 20% of the cost of housing (600.000 UAH). With the same loan term, in this case, you need to pay approximately 18.600 UAH per month. However, the amount of the overpayment is 1.465.680 UAH.
With an increased down payment (50%) and a term of 20 years, the monthly payment amount is UAH 11.630. Overpayment is UAH 1.290.960.
All figures given are approximate.
Mortgage lending
For example, we take the same two-room apartment in Podil, only now we consider a classic mortgage, the size of which is 17% per annum. The initial payment is 20%, the term of registration is 20 years. With simple calculations, it turns out that the monthly payment is 35.155 UAH. The overpayment is 6.037.200 UAH.
If it is possible to deposit 40% and take out a loan at 16% per annum, then the amount of payments will be 25.045 UAH per month. The overpayment is 4.120.800 UAH.
You can also choose a lending program of 30% of the down payment at a rate of 16% per annum. Then the apartment in mortgage will cost 35.170 UAH per month. The term is ten years. The overpayment is 2.120.400 UAH.
Again, we are saying that the numbers are approximate, for understanding the overall picture.
Comparison of payment methods for housing
Now let's compare the terms and amounts of payments and overpayments visually.
| First installment | Monthly payment | The need for proof of income | Overpayment | Payment term | Who is suitable for? | |
| Full payment | 3.000.000 UAH. | None. | None. | None. | One-time. | To anyone who has a large sum of money on hand. |
| Installment from the developer | 900.000 UAH. | 58.333 UAH. | None. | None. | 18 months (one and a half years), 36 months (three years). | If a person has almost the entire amount, but also a stable and high income. |
| The e-Housing program | 600.000 UAH. | 13.310 UAH (3%), 18.607 UAH (7%). | So. | 194.000 UAH (3%), 1.465.680 UAH (7%). | 240 months (20 years) | Military personnel, teachers, medical workers, IDPs, veterans, family members. |
| Mortgage loan | 600.000 UAH (17% per annum). | 35.135 UAH monthly. | So. | 6.037.200 UAH. | 240 months (20 years) | Suitable for everyone who does not have benefits. |
Let us note that each option has its own advantages. We can say that the most profitable option today can be considered "eOselya" at 3%, and the overpayment here is minimal. In this case, it is necessary to first correlate the requirements and the real state of affairs. Installments are good if the future owner is not officially employed, but he would have enough money for the down payment and monthly payments. Not everyone will be able to afford a mortgage loan for an apartment.
Visnovok
Certainly, purchase of an apartment – the event is extraordinary, it is full of joy and pleasant excitement. Ideally, it would be worth taking it right away, but let's be honest – not everyone has such a financial opportunity. When choosing a suitable instrument, we recommend taking into account a few simple tips on how to buy an apartment profitably:
- take a closer look at the "eOselya" program;
- calculate that the monthly payment does not exceed 40% of income;
- fix your credit history – close loans, pay off payments;
- find out about discounts – usually the price is reduced by 5-15%;
- Take real estate with high liquidity - this especially applies to new buildings that are carefully thought out, well-designed and built.
A little time to choose and calculate all future costs, and very soon you will own the perfect apartment of your dreams.