

Luxury real estate tax is a common household name for an additional tax burden. It occurs among owners of large residential real estate. There is no separate tax with this name in Ukrainian legislation. It is a tax on real estate, which is different from a land plot.
Our experts analyzed the explanations of the State Tax Service, the current norms of the Tax Code of Ukraine and the rules in 2026. Let's consider what area may give rise to an additional tax burden. Let's analyze how the tax on a house or apartment is calculated, what happens in the case of joint ownership.
What is a luxury tax in real estate?
Luxury tax is a colloquial name for a tax. It refers to a real estate tax. According to Article 266 of the Tax Code of Ukraine, it is paid by owners of residential and non-residential properties. The tax itself belongs to local authorities. Therefore, within the legislative limit, a specific rate is set by the relevant local council. The basic rules include:
- Payers can be individuals, legal entities and non-residents;
- the rate depends on the decision of the local authorities;
- Residential and non-residential real estate is subject to taxation;
- as of January 1 of the reporting period, the maximum rate is 1,5% of the minimum wage for 1 month2 taxable area;
- An additional tax increase of up to 25000 hryvnias per year is possible for individual large facilities.
Considering tax on real estate other than land, Article 266 of the Tax Code of Ukraine, in 2026, owners pay for 2025.
For what area of housing do you have to pay luxury tax?
Before determining how the real estate tax is calculated, the type of housing and its total area are determined. The Tax Code of Ukraine provides for a non-taxable area to reduce the tax base. For a residential building, this is 120 m2, for an apartment – 60 m2. When owning a house and apartment – 180 m2.
The presence of different types of real estate does not indicate automatic payment of luxury tax in Ukraine. After applying the preferential area, the tax base is determined. The main guidelines for housing:
- residential building – preferential area 120 m2;
- apartment – 60 m2;
- house and apartment together – 180 m2;
- apartment over 300 m2 – additional 25000 UAH per year;
- house over 500 m2 - additional 25000 UAH per year.
At the same time, the thresholds at 300 and 500 m2 are applied to a specific object or part of it, and not to the arithmetic sum of all apartments taken together.
Apartments
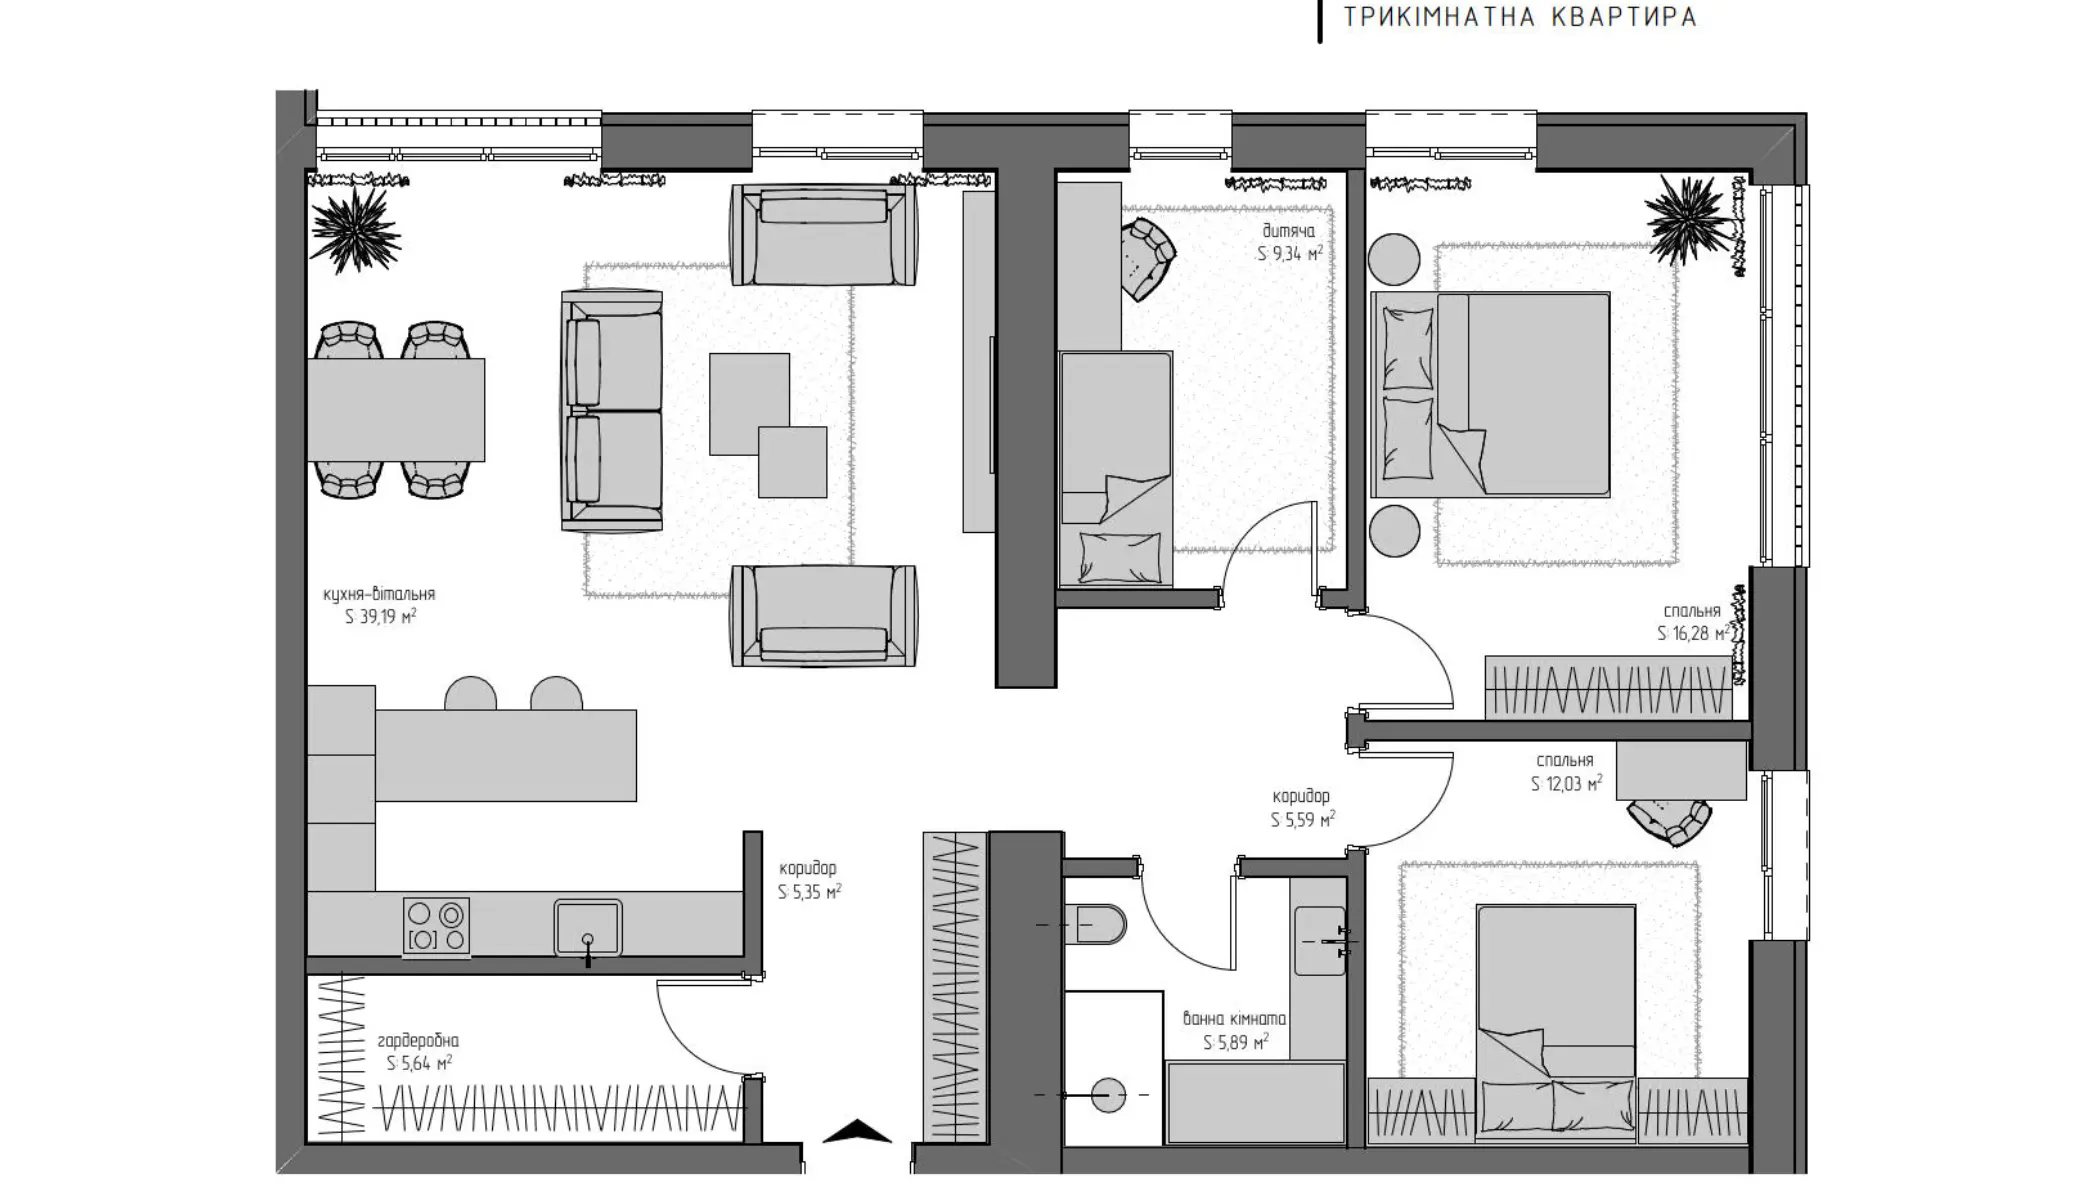
The total preferential area for the apartment is 60 m2If the owner has an apartment with an area of 80 m2, then the luxury tax on the apartment is calculated on 20 m2If the area of the apartment is 300 m2, then the additional 25000 hryvnias are not charged. This is due to the fact that the law contains the statement "exceeds 300 m2". If the area is 301 m2, then the amount of 25000 hryvnias will be added to the calculated tax.
For an apartment of 320 m22 at a rate of 120 UAH/m2 there are 260 m2 area subject to taxation: 320 – 60 = 260 m2. Basic tax: 260 x 120 = 31200 hryvnias. An additional 25000 hryvnias are charged, since the area of the apartment exceeds 300 m2. Total liability – 56200 hryvnias.
Private houses
The preferential area for residential buildings is 120 m2. House with an area of 160 m2 has 40 m2 taxable area. A different threshold applies to a large house. If the area of the house exceeds 500 m2, then 25000 hryvnias is added for the corresponding share. For a house with an area of 520 m2 conditional example:
- total area – 520 m2;
- preferential area – 120 m2;
- taxable area – 400 m2;
- rate for example – 120 UAH/m2;
- basic tax – 48000 UAH;
- additional increase – 25000 UAH;
- The total tax on luxury housing is 73000 hryvnias per year.
The actual amount will depend on the period of ownership of the property and the decision of the local council.
If you own an apartment and a house
The law on the luxury tax indicates that if the property includes an apartment and a house, then the total reduction of the base is carried out by 180 m2To determine the tax base, the areas of different residential types are taken into account together.
If the area of the house is 100 m2, apartments – 110 m2, then the total area is 210 m2. After applying the benefits: 210 – 180 = 30 m2 for calculation taking into account rates. The rule of additional 25000 hryvnias completely changes the logic here. Areas of different objects to reach the threshold of 300 or 500 m2 cannot simply be added together.
How is property tax calculated?
Residential property tax depends on the type, area, location, period of ownership, local council rate. The tax authority calculates the amount for individuals based on data from the State Register of Documents and the owner's property rights. Legal entities calculate their obligations independently. General algorithm:
- determine the total area of the objects;
- apply the preferential area determined by the PKU;
- determine the size of the area for taxation;
- find out the local government rate for the relevant type of property;
- take into account the period of ownership;
- add 25000 hryvnias for a house with an area of more than 500 m2 and apartments with an area of more than 300 m2.
The rate will not be uniform for all of Ukraine. A lower percentage may be set by local authorities and preferential terms may be offered. For the basic calculation, the maximum limit is 1,5% of the minimum wage per 1 m2 per year.
Example of tax calculation
In the example for Kyiv, we will take the maximum minimum wage rate of 1,5%, i.e. 120 UAH per 1 m2.
Example 1: apartment in Kyiv with an area of 320 m2
Taxable area: 320 – 60 = 260 m2.
Basic tax: 260 x 120 = 31200 hryvnias.
Due to the excess area: 31200 + 25000 = 56200 hryvnias.
Example 2: a house in Kyiv with an area of 520 m2
Taxable area: 520 – 120 = 400 m2.
Basic tax: 400 x 120 = 48000 hryvnias.
Due to the excess area of more than 500 m2: 48000 + 25000 = 73000 hryvnias.
These figures are examples of calculations. They are valid under the condition of ownership of the property throughout the year. The amount will be different if the local government rate changes. If you have a question about how to check the property tax, you can use the official DPS calculator.
Who doesn't pay the "luxury real estate" tax?
When it comes to the question of who does not pay property tax, tax rules provide for special cases. These are situations when the tax may not be charged. Separate rules in martial law apply to housing in occupied territories, in a combat zone, for destroyed, damaged facilities. Among the important cases are:
- the area of the dwelling does not exceed the tax-free norm;
- housing is uninhabitable or destroyed;
- real estate in occupied territories or in a war zone;
- certain properties owned by foster or large families;
- certain categories have special legislative privileges;
- benefits for religious, educational, and children's facilities.
Exemption from property tax does not automatically guarantee pensioner status. Local authorities often establish additional benefits within their powers.
When and how to pay tax?
Depending on who is the owner, the payment procedure is determined. When asking the question of when to pay real estate tax, an individual pays a certain amount after receiving a tax decision. A legal entity is responsible for calculating the tax independently. It submits a declaration and pays advance payments during the year. Notifications of the decision are sent by July 1 of the year following the reporting year. An individual has exactly 60 days to pay taxes.
Individuals
Regarding the tax, individuals do not submit an annual tax return on their own. Based on the data on real estate, the supervisory authority independently determines the amount. After receiving the notification, you need to check:
- total area;
- address of the object;
- share of ownership;
- type of property;
- the rate applied;
- period of ownership;
- preferential area;
- availability of additional 25000 hryvnias;
- the total amount of tax payable.
An individual can contact the tax authority to conduct a data reconciliation. This happens in situations where they do not agree with the calculation. You should not ignore a tax issue if the notification was not delivered in the prescribed manner.
For legal entities
Legal entities calculate the tax as of January 1 of the reporting year independently and submit a declaration. The entire amount for the year is divided into quarterly advance payments. Payment must be made by the 30th of the reporting month. It is important for a legal entity to correctly determine:
- residential or non-residential status;
- list of objects;
- local rate;
- the area of each object;
- period of ownership;
- availability of facilities with areas over 300 or 500 m2;
- an additional amount of 25000 hryvnias.
For a legal entity, there are special rules for filing a declaration if the ownership of a new object arose within a year. Penalties apply in case of late payment.
In what cases is the tax lower or not paid at all?
The tax amount may be lower than expected. This is possible if the local authorities set a rate lower than 1,5%. The status of the housing and the area in which it is located are checked separately. Among the practical factors that affect the amount, the following are distinguished:
- actual area of the object;
- share of a specific owner;
- number of objects;
- local council rate;
- month of acquisition and termination of ownership;
- the presence of legal benefits.
The presence of multiple apartments does not indicate that each of them has a separate benefit. Special rules for calculating the total area apply to multiple properties of the same type.
Tax in case of joint ownership
The question often arises of how to pay real estate tax in joint ownership. In this case, everyone is a payer and pays an equal share.
Example 1: two owners each with ½ share in an apartment of 350 m2.
Everyone has a share of 175 m2.2. A base is determined for each, taking into account the share and taxation rules. There is no reason for an additional 25000 hryvnias, since the share does not exceed 300 g2. Conditional calculation:
175 - 60 = 115 m2;
115 x 120 = 13800 hryvnias – the amount of tax per owner.
The total amount will be 27600 hryvnias per year.
Example 2: two owners each with ½ share in an apartment of 600 m2.
Each owner has a share of 300 m2. At maximum rate:
300 - 60 = 240 m2;
240 x 120 = 28800 hryvnias for each owner.
The total tax amount is 57600 hryvnias without the additional 25000 hryvnias being charged, since the area does not exceed 300 m2.
Thanks to the examples, it is clear that in case of joint ownership, not only the total area is checked, but also the legally registered share of each owner.
Visnovok
Tax on real estate other than land is a common name for a tax with special rules for large residential properties. To avoid mistakes, the owner should:
- check the charter and area in the state register;
- find out the rate in your own territorial community;
- do not confuse the thresholds for an additional 25000 hryvnias;
- verify ownership share;
- monitor tax notices and decisions;
- Do not miss the 60-day deadline for paying taxes.
In 2026, payment is made for 2025, taking into account the minimum wage for the marginal rate.


